Yogi Nelson, finance, Gold, Mining, precious-metals, Governance, Risk Management, Copper

The Rocks May “Rock”, But Can Management Roll?

Strategy & Stewardship — The First Pillar of the Mining SCOREcard™

by Yogi Nelson

The question contained in the title of this article is a fundamental question investors must ask themselves when evaluating a junior mining company. Precisely for that reason, in my introductory article to this series, I explained how my interest in gold and junior mining eventually led me to develop the Mining SCOREcard™. The SCOREcard includes a section dedicated exclusively to Strategy and Stewardship. I felt obligated to start with strategy and stewardship because, as I studied the industry, one lesson became increasingly clear: a great mineral deposit does not necessarily make a great investment.

As my son, who was 13 at the time, said to me—obvious! Nevertheless, when we look at junior mining companies, it is remarkably easy to become fascinated by geology. We read about drill intercepts, grades, resource estimates, potential extensions and discoveries that management describes as “world-class” or “transformational.” It’s as if we were hit by falling rocks and we lose perspective!

Having said that, rocks matter. Of course they do—a lot. However, no rock in the history of mining has made a decision. It just sits. In other words, rocks don’t make decisions. People do. Naturally, that is why the first pillar of my Mining SCOREcard™ is S — Strategy & Stewardship.

What Do I Mean by Strategy & Stewardship?

Strategy asks a fairly simple question: Does management have a credible plan for creating shareholder value?

Stewardship asks another: Can I trust these people to manage shareholder capital responsibly while pursuing that plan?

Those questions sound straightforward. Answering them isn’t.

Junior mining companies operate under unusual conditions. Almost none have revenue. Exploration companies may spend millions of dollars without knowing whether they will discover an economically viable deposit. They regularly return to capital markets for additional financing. Consequently, that makes management particularly important.

When I evaluate Strategy & Stewardship, I look at areas including the investment thesis, CEO and executive-team quality, Board composition, management’s discovery or mine-building track record, capital allocation, insider ownership, corporate governance, strategic vision, communication and transparency, and alignment with shareholders.

But the SCOREcard is not intended simply to check boxes. Checking boxes is for junior analysts, but not for senior analysts of junior mining companies. The SCOREcard is about asking questions!

What Exactly Is the Strategy?

Suppose an exploration company tells investors: “We intend to discover a multimillion-ounce gold deposit and sell it to a major mining company.” Is that a strategy? Maybe—maybe not. It all depends. It could be a hope, a dream, or something in between.

A wise investor would ask: How large a deposit? What grade? What metallurgy? In what jurisdiction? At what stage does management intend to sell? What type of company would realistically acquire it? What evidence suggests that management has the experience to get the project to that point?

In other words, “Discover gold and sell the company” may be an aspiration. It isn’t necessarily a strategy.

I want management to explain in plain English the strategy, not just declare it.

Who Is Managing My Money?

I have spent much of my professional career around governance, compliance and public administration. Perhaps because of that background, I tend to look beyond biographies and titles.

A CEO may have 25 years of mining experience. That sounds impressive. But what kind of experience?

Running operations for a major producer is not necessarily the same as managing a cash-constrained junior explorer. Does the CEO know how to allocate scarce exploration capital? Raise money? Manage dilution? Communicate with junior-mining investors? Build and retain a strong geological team?

And where the CEO lacks experience, has management built a team and Board that compensate for those weaknesses?

I don’t expect executives to know everything. In fact, I am impressed by those who are self-aware enough to know what they don’t know.

Capital Allocation May Matter More Than Capital Raising

Junior miners need money. That means dilution is often unavoidable. I therefore don’t automatically consider dilution evidence of poor stewardship. That is not the right question. For my money, I ask: What did management create with the capital it raised?

Imagine a company increases its share count substantially but uses that capital to expand a resource from 500,000 ounces to 3 million ounces and complete a positive economic study.

Was that bad dilution? Not necessarily. The better question is whether management created more value per share than it surrendered through dilution. The distinction is important.

Dilution is not necessarily the enemy. Value-destructive dilution is.

I also want to know who participated in financings and on what terms. A long-term strategic or institutional investor may behave differently from investors chasing short-term momentum. Large investors can also create concentration and influence risks.

Financing changes more than the number of shares outstanding. It can change the character of the shareholder base.

Independence Is More Than a Label

Board independence is essential. A director may officially be described as “independent,” but I want to understand that person’s relationships with management and the company. Don’t fall for the label on the wine; taste the wine to see if it is authentic.

Who nominated the director? Does the director have significant business relationships with the CEO? Does the director receive consulting fees? How are conflicts handled? Are important Board committees genuinely independent? More importantly, is there evidence that directors actually challenge management?

Independence is not merely a director’s label. It is a relationship to management—and ultimately a pattern of behavior.

Promotion Versus Evidence

Junior mining is also a promotional business. Management needs investors. Investors need a reason to provide capital. I therefore expect some salesmanship. Words such as “exceptional,” “transformational” and “world-class” don’t particularly impress me. Instead, I go to the source.

What do the regulatory filings and independent technical reports actually say? Do the grades, widths, continuity, metallurgy and economics support management’s enthusiasm? If management’s presentation is enthusiastic while the technical evidence is strong, I may simply be looking at normal salesmanship. But if management’s language repeatedly outruns the evidence, I have a stewardship problem.

Promotion is not necessarily a governance weakness. Promotion that consistently outruns the evidence is.

Red Flags Are Questions, Not Convictions

Developing the SCOREcard has also reminded me of something about my own analytical approach. I am naturally skeptical, and after 33 years in government and politics, well, what can I say…

When I see excessive compensation, frequent dilution, promotional communications or related-party transactions, my antenna goes up. However, a red flag is not necessarily a verdict. Life has many surprises. Therefore, there may be reasonable explanations. My job as an investor is to identify the concern, develop plausible alternative explanations, examine the evidence and then reach a conclusion.

In other words: Identify the red flag. Develop the innocent explanation. Test both against the evidence. Then score it. That discipline matters because several individually explainable issues can also form a troubling pattern.

High compensation may be explainable. Dilution may be explainable. Promotional communications may be explainable. Related-party transactions may be explainable. But if all four consistently benefit insiders at the expense of shareholders, I may be looking at something very different.

Great Geology Is Not Enough

Let’s return to the reason Strategy & Stewardship is the first pillar of the Mining SCOREcard™. It’s important.

A company can control an extraordinary mineral deposit and still destroy shareholder value through poor financing decisions, excessive dilution, bad acquisitions, weak governance or self-dealing. Conversely, capable and disciplined management can sometimes create substantial shareholder value from an asset that initially appears less spectacular.

The asset and its stewards therefore have to be evaluated separately. For me, the ultimate Strategy & Stewardship question is surprisingly simple: Do I trust these people to allocate my capital intelligently and ethically over the many years it may take to turn geological potential into shareholder value?

If I cannot answer that question satisfactorily, excellent drill results alone may not be enough.

Next week, I will move to the second pillar of the Mining SCOREcard™:

C — Commodity.

Because after deciding whether I trust the people managing my investment, I want to understand exactly what commodity—and what kind of economic opportunity—I am investing in.

Sincerely,

Yogi Nelson
Austrian economics, Blockchains, cryptography, Decentralized, Digital Currency, finance, Gold, Governance, International Finance, Mining, Tether, tokenization, Yogi Nelson

Who Can Be Trusted? Custody, Verification, and the Problem of “Proof”

by Yogi Nelson (Nelson Hernandez)


You can own gold tokens on the blockchain. Yes, many do. After purchase, the tokens are visible on their screens. Using blockchain, gold token holders can track every transaction ever made. Of course, that feels precise. You might say modern… and perhaps reliable. However, one small, pesky question can ruin the moment: Where is the metal? And just as important: Who says it’s there—and how do you know?

Let’s not be naive—a token representing gold is only as good as the system that ensures that gold actually exists. Is that system a blockchain? Yes, but there is more to it—a lot more. The keys are custody, verification, and proof.


The Chain Behind the Token

Much has been written about blockchain as a trust mechanism—and for good reason. For instance, it records transactions. Blockchain also prevents double-spending. Moreover, it creates a permanent ledger. Everyone who understands blockchain agrees. However, when you understand the tech, you know blockchain does not:

  • Store gold
  • Inspect vaults
  • Verify bar numbers
  • Audit inventory

Those responsibilities fall to a chain of real-world actors:

  • Custodians (vault operators)
  • Auditors (third-party verifiers)
  • Issuers (token creators)
  • Sometimes insurers

Each of these introduces:

  • Judgment
  • Process risk

And each becomes a point where trust must be earned. Governance teaches what questions to ask. Let’s walk through that exercise now.


Custody: The First Point of Failure

What is the foundation of tokenization? If you answered custody, move to the front of the class. The basic premise is simple: a physical asset is stored somewhere, and a digital token represents it. However, life is often not simple, because beware—simplicity is often deceptive. Therefore, you need to ask penetrating questions such as:

  • Is the metal allocated or unallocated?
  • Is it segregated or pooled?
  • Is it held in a recognized vault?
  • Who has legal claim in the event of insolvency?

These are not technical distinctions. They are legal and operational realities.

A token holder may believe they “own gold,” but what they actually own depends entirely on the custody structure. In some cases, they own a specific bar, but it could instead be a claim on a pool or, worse yet, a claim on a claim. That’s why we need to discuss verification.


The Problem of Verification

Let us assume, for the moment, that the gold is indeed stored in a reputable vault. Fine. The next question becomes: Who verifies that it is actually there? This is where the concept of “proof” enters the discussion. Tokenized systems often rely on:

  • Periodic audits
  • Attestations
  • Internal reporting

These vary significantly in quality. For example, an audit typically involves:

  • Independent verification
  • Physical inspection
  • Reconciliation of records

By contrast, an attestation may simply confirms that a statement provided by management appears reasonable Those are not the same thing. Yet in many tokenized systems, the distinction is not clearly communicated. As is said in India, “what to do”? The answer: proof of reserves.


Proof of Reserves: A Partial Solution

In response to growing skepticism, many token issuers now promote “proof of reserves.” Promoters may try to present proof of reserves as a technological breakthrough. It’s not. In reality, it is a hybrid concept. Proof of reserves may show:

  • The number of tokens issued
  • The assets claimed to back them

But it does not always prove:

  • That the assets are unencumbered
  • That they are not pledged elsewhere
  • That they are held in the stated form

In other words: proof of reserves can confirm consistency—but not necessarily reality. Is it a step forward? You bet. When it comes to governance, there is no substitute for precision, and even that has its challenges, as explained below.


The Illusion of Precision

One of the more subtle, but real, risks in tokenized systems is the illusion of precision. After all, it’s a system built on a foundation of math and cryptography. A blockchain ledger may show:

  • Precise quantities
  • Exact timestamps
  • Strict ownership

This creates a sense of certainty. But precision in the digital layer does not guarantee accuracy in the physical layer. You can have perfect records of imperfect information

This is not a flaw in the technology. It is a limitation of what the technology can verify.


Trust Has Not Disappeared—It Has Moved

The idea of “trustless” systems suggests that trust is no longer required. Wrong. In reality, trust has not disappeared—it has simply moved. For the better? Maybe. Instead of trusting banks, you are trusting:

  • Custodians
  • Auditors
  • Issuers

The question is not whether trust exists. That question is evergreen. The questions are: Where does trust reside—and whether it is justified. Align those questions, and trust increases. Hence, we next examine alignment and misalignment.


When Custody and Governance Align

Strong systems recognize these limitations and address them directly. They incorporate:

  • Reputable, third-party vaults
  • Clear legal ownership structures
  • Regular, independent audits
  • Transparent reporting

More importantly, they establish:

  • Oversight mechanisms
  • Accountability frameworks

In such systems, custody is not just a function—it is governed. And governance ensures that:

  • Processes are followed
  • Risks are identified
  • Discrepancies are addressed

Misalignment–When Governance Fails

Weak systems tend to rely on:

  • Brand perception
  • Marketing language
  • Selective disclosure

They may may also emphasize:

  • Technology
  • Innovation
  • Accessibility

While minimizing discussion of:

  • Custody arrangements
  • Audit rigor
  • Legal structure

These are the systems where problems emerge. Not immediately. Eventually. And always. As an investor, your duty is to ask 100+ probing questions.


The Role of the Investor

This raises an uncomfortable reality: The burden of understanding often falls on the investor. Investors must ask:

  • Where is the asset?
  • Who holds it?
  • How is it verified?
  • What happens if something goes wrong?

These are not easy questions—but necessary ones. Without clear answers, the token becomes an assumption—not an asset. You know what they say about assumptions!


What Does It All Mean

Tokenization promises efficiency, transparency, and access. Awesome benefits. However, it does not eliminate the need for:

  • Custody
  • Verification
  • Governance
  • Judgment

Tokenization makes those elements more important. Once an asset is tokenized, it becomes:

  • Easier to trade
  • Faster to distribute
  • Simple to scale

Which also means weaknesses become magnified.

In conclusion the buyer is purchasing more than a token. Investors are buying a system of trust—a system that must be scrutinized, not assumed.


Until next time,

Yogi Nelson (Nelson Hernandez)

Austrian economics, Banking, Blockchains, Board of Directors, cryptography, Digital Currency, finance, Governance, International Finance, Mining, sec, tokenization, Yogi Nelson

You Can Tokenize Assets—But Not Human Judgment: Why Governance Still Matters

by Yogi Nelson (Nelson Hernandez)

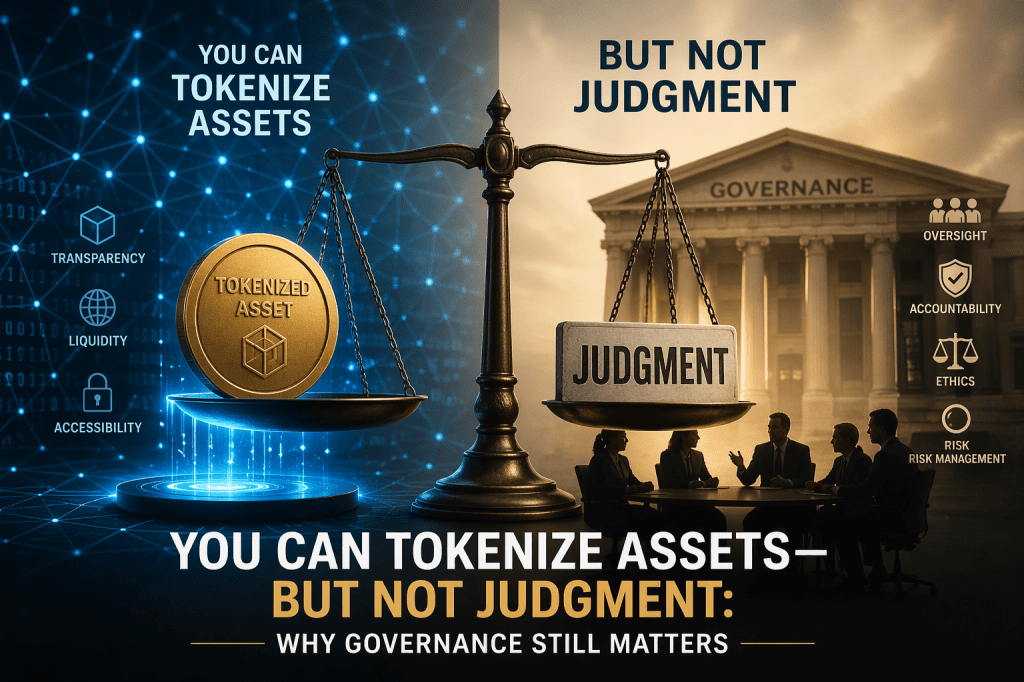
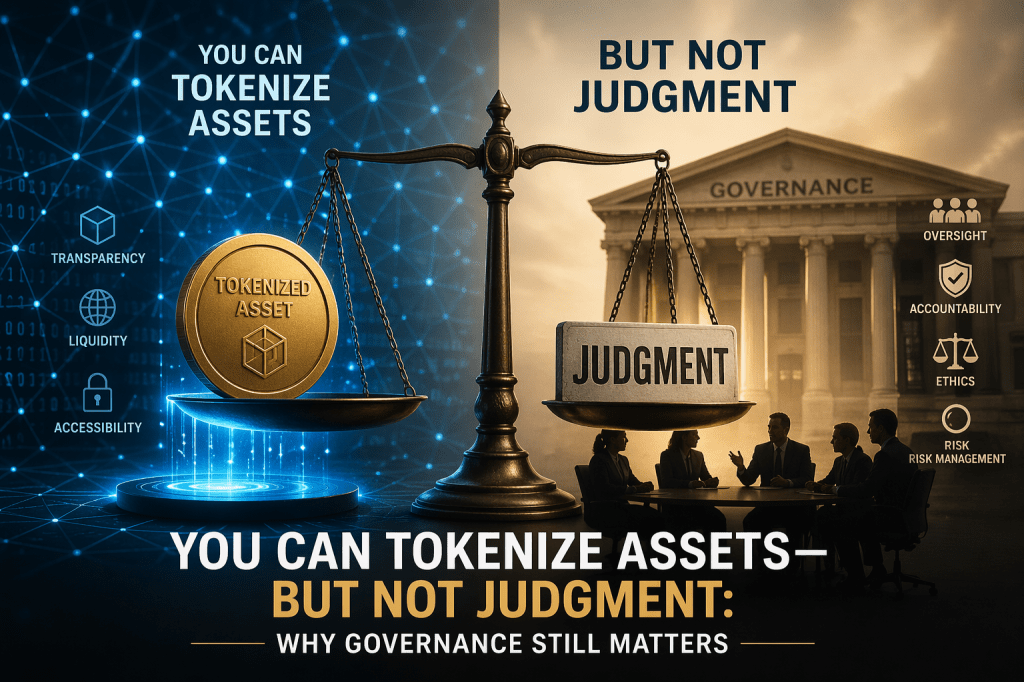
You can tokenize assets. You can tokenize gold, silver, and just about anything of value. But you cannot tokenize judgment. That may be the most important limitation in the entire digital asset conversation.

Tokenization promises transparency, liquidity, and accessibility. It’s a compelling vision—and one that is partially true. But behind every tokenized asset lies something far more fundamental than code: Governance.

Who verifies the asset exists?
Who ensures it is properly stored?
Who makes capital decisions?
Who is accountable when things go wrong?

These are not technical questions. They are governance questions.

The idea of “trustless” systems is often misunderstood. Tokenization doesn’t eliminate trust—it simply shifts it. And without strong governance, that trust becomes more fragile, not less.

As tokenized metals evolve, the real challenge won’t be technological. It will be structural. Investors are not relying on code alone—they are relying on the people, systems, and decisions behind it. Those are governed—not programmed.

Until next time,

Yogi Nelson (Nelson Hernandez)

Austrian economics, Banking, Blockchains, Board of Directors, Decentralized, Digital Currency, Gold, Governance, International Finance, Mining, sec, tokenization, Uncategorized, Yogi Nelson

You Can Tokenize Assets—But Not Human Judgment: Why Governance Still Matters

by Yogi Nelson (Nelson Hernandez)

Tokenization, the Promise and the Gap

Can assets be tokenize? Absolutely yes. The more important question is, can judgement be tokenize? Absolutely not. Ironically, our inability to replace human judgment is the most important limitation in the entire digital asset conversation—because while ownership can be digitized, governance, with its inherently human only elements, cannot be automated away. Decision making requires people. Risk management is a people business. Accountability is evergreen. There is no alternative.

Tokenization has indeed captured the imagination of markets, technologists, and investors alike. By converting real-world assets—such as gold, silver, and other metals—into digital tokens on a blockchain, proponents promise greater transparency, liquidity, and accessibility. It is a compelling vision–one that is also incomplete. Why is that? Because behind every tokenized asset lies something far more fundamental than code: a system of trust, accountability, and decision-making called governance!


What Tokenization Actually Does—and Does Not Do

At its core, tokenization is a method of representation. A token may represent:

  • A bar of gold in a vault
  • A share of a mining project
  • A claim on future production

The blockchain on the other hand provides:

  • A ledger
  • Transparency of transactions
  • Immutable record-keeping

These are important innovations. Nevertheless, neither answer critical questions:

  • Who verifies that the gold actually exists?
  • Who ensures it is properly stored and insured?
  • Who decides how a mining project allocates capital?
  • Who steps in when something goes wrong?

These are not technical questions. They are governance questions.


The Illusion of “Trustless” Systems

One of the most common narratives in tokenization is the idea of a “trustless” system—one in which technology replaces the need for trust. This is misleading and here’s why.

Tokenized metals still depend on:

  • Custodians
  • Auditors
  • Operators
  • Issuers

Each of these actors introduces:

  • Judgment
  • Incentives
  • Potential conflicts

Blockchain may reduce certain forms of risk, but it does not eliminate the need to trust: it simply shifts where that trust is placed. What’s worse, without excellence in governance the trust becomes more fragile and opaque–not less.


Where Governance Enters the Equation

Governance is not a theoretical construct. It is a practical framework that answers fundamental questions:

  • Who is responsible for what?
  • How are decisions made?
  • How are risks monitored and managed?
  • How are stakeholders protected?

In the context of tokenized metals, governance must address several layers:

1. Asset-Level Governance. Is the Underlying Asset:

  • Real
  • Properly stored
  • Independently verified

2. Operational Governance. Are the Entities Involved:

  • Competent
  • Accountable
  • Subject to oversight

3. Financial Governance. How are:

  • Revenues managed
  • Costs controlled
  • Capital allocated

4. Disclosure and Transparency. Are investors receiving:

  • Accurate information
  • Timely updates
  • Balanced reporting

These are the same governance questions that exist in traditional finance. Tokenization does not remove them. It amplifies them.


The Mining Parallel

The tokenization of metals ultimately connects back to physical mining. Before a token can represent gold or copper, that metal must be:

  • Discovered
  • Developed
  • Extracted

Mining is capital-intensive, high-risk, and operationally complex. To paraphrase legendary natural resources investor, Rick Rule, weak governance in mining leads to poor outcomes—regardless of asset quality.

Projects fail not only because of geology, but because of:

  • Poor capital discipline
  • Lack of oversight
  • Conflicts of interest
  • Weak boards

Tokenization does not fix these problems. If anything, it can obscure them—by placing a digital layer over an imperfect foundation.


Governance as a Value Multiplier

When governance is strong, it does more than reduce risk. It creates value. In tokenized metals, strong governance can:

  • Increase investor confidence
  • Improve capital access
  • Enhance credibility with institutions
  • Support long-term sustainability

Investors are not simply buying tokens. They are buying the integrity of the system behind those tokens and that integrity is built through governance.


The Role of Boards and Oversight

At the center of governance is oversight of management. Boards and governing bodies must ensure that:

  • Systems are functioning as intended
  • Risks are identified and addressed
  • Decisions are aligned with long-term value

In many tokenization discussions, governance is treated as secondary—an afterthought once the technology is in place. What a mistake! To be most effective governance must be designed in from the beginning—not added later.


The Risk of Getting It Wrong

The risks of weak governance in tokenized metals are significant:

  • Misrepresentation of assets
  • Operational failures
  • Loss of investor confidence
  • Regulatory intervention

In a worst-case scenario, technology can accelerate the spread of problems rather than contain them. A flawed system, once tokenized, becomes:

  • More scalable
  • More visible
  • More fragile

Regulation Is Not a Substitute

Commentators may argue that regulation will fill the governance gap. That is not the job of the government, nor should it be. As a former government regulator I understand regulation is important—but it is not sufficient. Regulators:

  • Set minimum standards
  • Enforce compliance

They do not:

  • Run companies
  • Make daily decisions
  • Replace effective boards

Building Governance into Tokenization

For tokenized metals to reach their potential, governance must be integrated into the design of the system. This includes:

  • Clear roles and responsibilities
  • Independent oversight
  • Robust audit processes
  • Transparent reporting
  • Alignment of incentives

It also requires a shift in mindset, from technology-first, to structure-first.


What This Really Means

Tokenization is a powerful tool. It has the potential to reshape how assets are owned, traded, and accessed. However, it is not even a poor substitute for governance. Rather, it is a layer built on top of governance.

Get the governance right, and tokenization can enhance value, transparency, and trust. Get it wrong, and no amount of technology will compensate. Because in the end investors do not rely on code alone.
They rely on the people, structures, and decisions behind it.
And guess what? Those are governed–not programmed.

Until next time,


Yogi Nelson (Nelson Hernandez)

Board of Directors, Mining, Risk Management, Yogi Nelson

Governance as a Force Multiplier: The Discipline That Determines Outcomes

by Yogi Nelson

Over the course of these articles (which will soon be published as a book), we have examined governance not as a theoretical construct, but as a practical system of discipline—one that operates quietly in the background, yet determines whether a junior mining company creates value or destroys it. Essentially, a forceful argument in favor of disciplined governance has been presented—an effective one at that.

We began with a simple premise: geology may create opportunity, but governance determines outcomes. That idea has carried through every chapter. But we didn’t leave it at that. Instead, we also explored board composition—not as a checklist of credentials, but as a deliberate assembly of judgment. What else was accomplished?

First, the notion of independence—not as a regulatory requirement, but as a safeguard against groupthink—was highlighted. Second, we discussed capital allocation as a test of discipline, where decisions made under pressure reveal whether fiduciaries are truly acting in the long-term interest of shareholders. Given the comprehensive nature of the book, we didn’t stop there; we continued.

The right people in the room change everything—governance is where discipline begins

For instance, we examined jurisdictional risk and learned that political geography cannot be avoided—it must be governed. Of course, management oversight was emphasized; therefore, we made a point of noting that alignment is not assumed—it must be structured, monitored, and, when necessary, enforced. Was that the end? No, it wasn’t; we carried on and dove into other substantive issues, including technical and engineering considerations.

In the section related to technical complexity and the limits of expertise, we pointed out that board members do not need to be engineers. However, they must know when and how to question engineers. If an engineer cannot explain what he is doing to a board of reasonably intelligent people, the problem is probably with the engineer—not the board. We explored compensation, not as a reward system, but as an instrument that either aligns incentives—or distorts them. In other words, money talks. Last, we discussed transparency and communication, recognizing that trust is not built through promotion, but through consistency and credibility over time.

Regardless of the specific issue, one theme has remained constant: governance is not static. It is not a document, a committee, or a policy manual. It is a behavior.

From Structure to Behavior

Mining is a people business. That may surprise some who think of mining as machines, drills, and equipment. Analysts who fail to consider the people side of the business miss half the story.

A well-structured board does not guarantee good governance. Policies do not enforce themselves. Committees do not think. People do. Governance becomes real only when individuals—directors, executives, and advisors—exercise judgment under conditions of uncertainty. The distinction matters.

A company may have all the formal elements of governance in place—independent directors, audit committees, compensation frameworks—and still fail if those structures are not animated by discipline.

Conversely, a smaller company with fewer formalities but strong, principled leadership can outperform because governance is practiced, not just documented. Governance, therefore, is not defined by what exists on paper, but by what happens in the room.

The Compounding Effect of Discipline

In junior mining, most outcomes are not determined by a single decision. They are the result of a series of decisions made over time—often under pressure and with incomplete information. This is where governance acts as a force multiplier. The direction of that force multiplier depends on discipline.

Good governance does not guarantee success. But it increases the probability of making sound decisions repeatedly. And over time, those probabilities compound. Whether the compounding effect is positive depends on discipline. When it is positive, expect:

  • Capital is allocated more carefully
  • Dilution is managed more thoughtfully
  • Projects are advanced more deliberately
  • Risks are identified earlier
  • Mistakes are corrected faster

The effect is subtle at first. But over multiple cycles—financing, exploration, development—the difference becomes profound. Companies with disciplined governance tend to survive downturns, preserve optionality, and position themselves for opportunity when conditions improve. Those without it often do not.

Governance in Adverse Conditions

It is easy to appear well-governed when markets are strong. (As they say in Puerto Rico, even a pumpkin can roll downhill.) Capital is abundant. Errors are masked. Optimism fills the gaps where discipline should be.

The real test of governance occurs in adverse conditions. When capital is scarce, decisions become harder. Trade-offs become sharper. The consequences of error become more immediate. Staff and board members may turn on each other. Accusations start. Negativity breeds negativity. This is where governance reveals itself.

  • Does the board protect shareholder capital—or rationalize dilution?
  • Does management adjust strategy—or continue pursuing sunk costs?
  • Are risks confronted honestly—or deferred?

In difficult markets, governance is no longer abstract. It becomes visible. And it becomes decisive.

Alignment: The Core of Fiduciary Responsibility

Misalignment is the root cause of most governance failures. Hence, at its core, governance is about alignment.

  • Management and shareholders
  • Short-term decisions and long-term value
  • Incentives and outcomes
  • Risk-taking and accountability

Do not blame intelligence or lack of effort, as those are seldom the fundamental reasons for failure. Misalignment is the culprit.

When incentives reward growth over value, dilution follows. And when oversight is weak, accountability erodes. What happens when boards defer rather than challenge? Small issues become large problems.

Assuming the analysis is correct, it begs the question: what is the solution? The solution is proper alignment—asking uncomfortable questions, resisting easy answers, and staying focused on the prize: long-term value creation.

The Role of Judgment

No framework, no checklist, no policy can substitute for judgment. Governance requires the ability to make decisions when the data is incomplete, the outcomes are uncertain, and the stakes are high. This responsibility cannot be outsourced to a board nor to an AI agent. This is particularly true in junior mining, where technical, financial, and geopolitical variables intersect.

Strong governance recognizes the limits of certainty. Accordingly, it does not seek perfect information, because that rarely exists on a timely basis. Instead, it seeks informed judgment. How does it do so? By creating an environment where that judgment can be exercised independently, rigorously, and without undue influence.

What Endures

The only certainty in life is change. Markets change. Commodity prices rise and fall. Jurisdictions shift. Technologies evolve. While everything changes, the application of certain underlying principles of governance endures. And what are those principles? Discipline, independence, accountability, and alignment.

These are not trends. They are constants. Companies that embed these principles into their decision-making processes are better equipped to navigate uncertainty—not because they can predict outcomes, but because they can respond to them effectively.

A Final Observation

In junior mining, much attention is placed on discovery. That certainly makes sense. After all, discovery creates possibility. Does possibility equal value? No, it does not.

Value is created through a series of disciplined decisions—over time, under uncertainty, and often without recognition. That is the work of governance. It does not generate headlines. It does not appear in drill results—directly. Yet it determines whether opportunity becomes outcome.

Conclusion

Governance is often viewed as a constraint—a set of rules that limits action. In reality, it is the opposite. It is a force multiplier that enhances the quality of decisions, improves the resilience of organizations, and increases the probability of success.

In a sector defined by uncertainty, that is not a small advantage. It is the difference.

Until next time,

Yogi Nelson