Board of Directors, Copper, Environment, finance, Gold, International Finance, Lithium, Mining, Nickel, palladium, platinum, precious-metals, Silver, Uncategorized, Yogi Nelson

Pillar “O”is for Opportunity—Could, Might, Maybe…Show Me!

Opportunity — The Third Pillar of the Mining SCOREcard™

by Yogi Nelson

Welcome to the third pillar of the SCOREcard: O for Opportunity! This is where junior mining investing gets really interesting–potential profits or dollar disaster! No longer is the question what does the company have today. We ask what it might have tomorrow. Keep in mind, the word “might” could mean possibility or strength!

What Are We Really Buying?

Invest in a junior mining company, equals buying an unfinished business. There may be no mine. No revenue. No earnings. Perhaps not even a defined mineral resource. Ouch! If true what am I buying? The big “O”–Opportunity.

Maybe the company has a substantial resource that could become a mine. Or drilling could expand the existing deposit. Perhaps the company controls an entire district containing multiple targets. What if management believes the geology suggests something much larger than anything yet demonstrated. Note the modal verbs in bold, e.g. could, maybe, believes, etc. Are there possibilities? Yes. Could there be value. Yes. Show me–yes!
Existing Value: Show Me What You Have

Start with Existing Value. What has the company already demonstrated? Not press releases? Technical studies from creditable sources. Has it identified a mineral resource? How large is it? What is the grade? How much is inferred, indicated or measured? Has metallurgy been tested? Has the company completed an economic study?

In other words: Show me what you have—not what you hope you have.

This distinction matters. Under established mining disclosure standards, confidence increases as resources move from inferred to indicated to measured. A resource is not automatically a reserve, and mineralization is not automatically an economically viable mine. Sounds like technical or legalse, right? Not to a sophisticated investor using the SCOREcard. They are fundamental.

A million ounces demonstrated through sufficient drilling and geological work are not comparable to management saying, “We think there could be several million ounces here.” Could they be right? Who care! Don’t give equal points for evidence and enthusiasm.

Expansion Value: Can It Get Bigger?

Next comes Expansion Value. Suppose the company has already discovered a legitimate deposit. Excellent. Now I want to know: Is that all there is?

Perhaps the deposit remains open along strike. Maybe it remains open at depth. Maybe additional drilling between existing holes could add ounces or increase geological confidence. Maybe, perhaps, could be, etc. Keep in mind, opportunity without uncertainty wouldn’t be opportunity—it would already be value. That’s the right sentiment.

This is one of the attractions of junior mining. A company can create value not only by finding a deposit but by demonstrating that the deposit is considerably larger than originally believed. But again, show me the evidence.

Where are the existing drill holes? Where is the mineralization open? What geological evidence suggests continuity? Is management drilling logical extensions of something already discovered, or drawing colorful arrows on a presentation? Arrows are cheap. Drill holes are not.

District Value: One Deposit or Something Much Bigger?

District is the word every explorer or junior mining company dreams. A world of multiple deposits. Various types, e.g. gold, copper, and silver. Many deposits. Oh the joy! District Value is the term.

Perhaps the flagship deposit is only the first discovery. Nearby targets may share the same geological structures, alteration patterns or mineralization. There may be multiple deposits capable of eventually sharing roads, power, processing facilities and other infrastructure. The opportunity potentially changes.

“How big can this deposit become?” is the inquiry. That’s a much bigger question. However, big claims require bigger evidence. After all, we all know land packages look wonderful on investor presentations. Thousands of hectares sound impressive. But owning a large amount of dirt doesn’t necessarily mean you own a large amount of value. I want to know why management believes additional deposits exist.

Geophysics? Geochemistry? Surface samples? Historic workings? Previous drilling? Geological analogues?Investors need to take the Missorui motto to heat: Show me the evidence.

Blue Sky: Where Dreams Meet Drill Bits

Finally, we arrive at perhaps the most exciting phrase in junior mining: Blue-sky potential. This is where to quote Linda Ronstadt: “Its so easy to fall in love, its so easy to fall in love…” Everyone loves a blue sky, including your truly. The possibility of a transformational discovery is one of the reasons people invest in junior explorers in the first place.

A few drill holes can sometimes completely change how the market views a company. Red alert–blue sky is also where imagination can outrun evidence. Management presentations are filled with words such as “potential,” “prospective,” “district-scale,” “world-class” and “analogous.” Sure. Maybe.

The Mining SCOREcard™ doesn’t tell me to ignore blue-sky potential. Quite the opposite. I want to identify it. I put it in the correct box: Conceptual Opportunity. Conceptual opportunity deserves consideration, not necessary your dollars.

Not All Ounces Are Created Equal

Opportunity isn’t merely about getting bigger and better. I’ll explain. Suppose additional drilling adds another million ounces of gold. Wonderful. But where are those ounces?

Are they close to existing infrastructure? Are they deeper? Lower grade? Metallurgically complicated? Do they potentially extend mine life? Could they improve project economics? In other words, more isn’t automatically better.

The same principle applies to resource conversion. Drilling that converts inferred resources into higher-confidence categories may not produce a spectacular headline. No giant new discovery. No fireworks. Yet reducing uncertainty can create substantial value. Sometimes proving what you already think you have is just as important as discovering something new.

Catalysts Matter

Does opportunity have a time dimension–it sure does. I want to know what catalyst could cause a re-rate of market value, e.g. drilling, permitting, etc.

I also ask another question: How much money will it take to get there?

A company may have extraordinary geological opportunity but require $50 million of additional exploration before investors know whether the thesis works. Where does that money come from? Remember our first pillar: Strategy & Stewardship. Opportunity does not exist in isolation from capital allocation.

Opportunity Must Be Earned

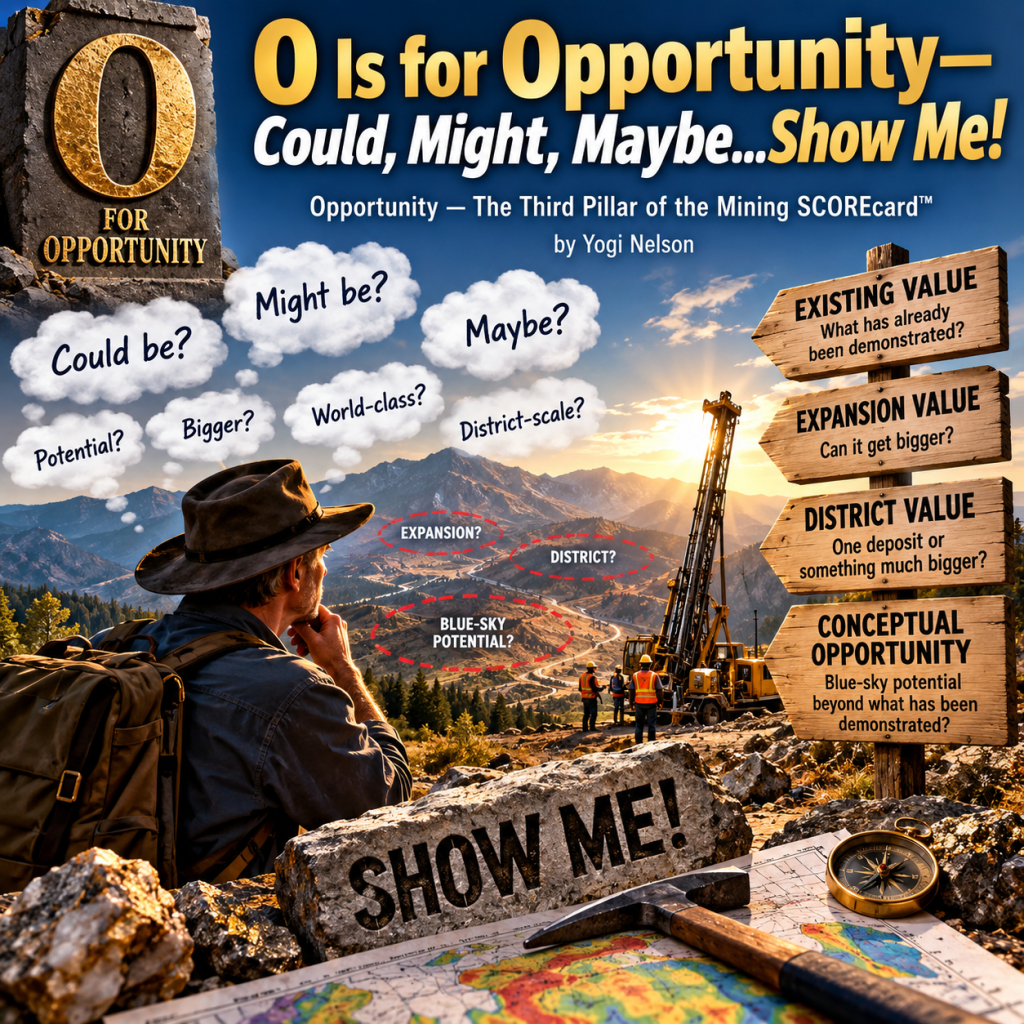
The Mining SCOREcard™ therefore separates Opportunity into four broad categories:

Existing Value — What has already been demonstrated?

Expansion Value — How much larger or better could the existing deposit become?

District Value — Could the property contain multiple deposits or a much larger mineralized system?

Conceptual Opportunity — What plausible blue-sky potential exists beyond what has been demonstrated?

As we move down that list, potential may increase; certainty decreases. That’s the trade-off. The purpose of the SCOREcard isn’t to eliminate speculation. Junior mining would be pretty boring without speculation! The purpose is to distinguish informed speculation from wishful thinking. We can recognize extraordinary potential without pretending that potential has already become reality. That’s Opportunity and it requires a Show Me attitude!

Sincerely,

Yogi Nelson
Board of Directors, Copper, Gold, Governance, Mining, Nickel, palladium, platinum, Silver, Yogi Nelson

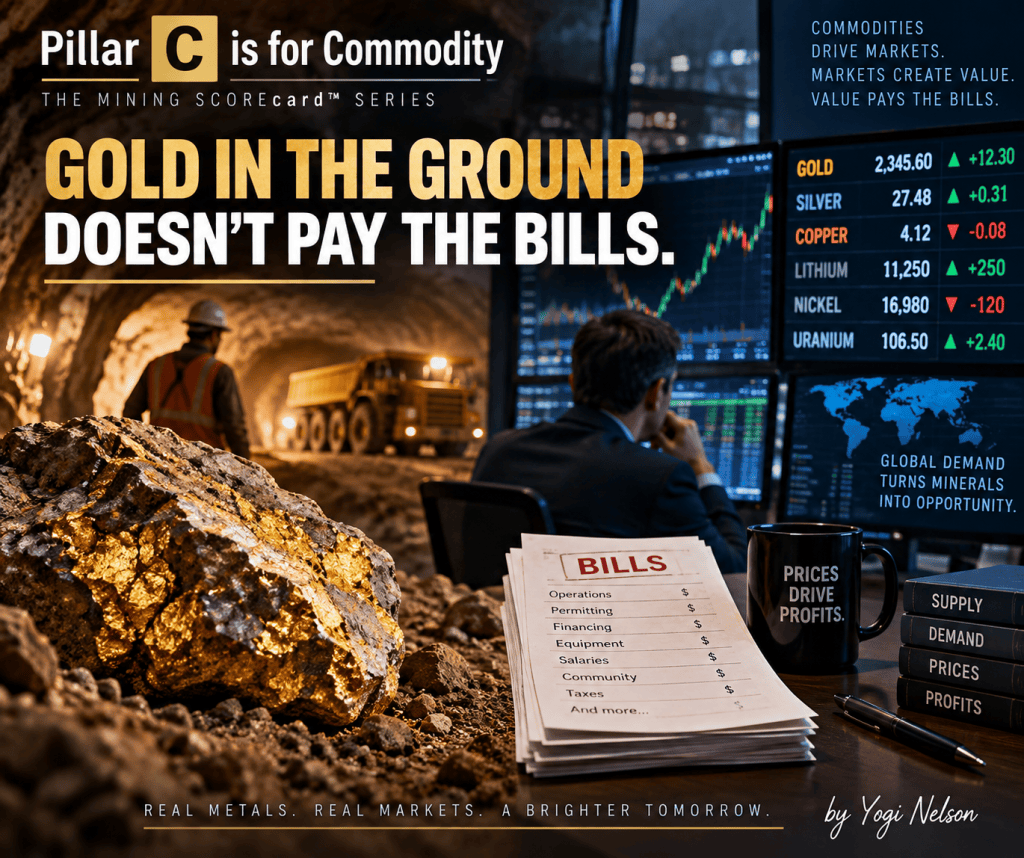
Pillar “C” Is for Commodity: Gold in the Ground Doesn’t Pay the Bills

by Yogi Nelson

Previously, I mentioned the Mining SCOREcard™  starting with Pillar 1: Strategy & Stewardship.  The basic premise: Rocks don’t make decisions. People do.  Now we move onto Pillar 2: “C”, Commodity.

Management may be mining superstars. The geology may be exciting. Drill results may look terrific. All fantastic.  Nevertheless, eventually somebody must be willing to part with their legal tender for the gold, silver, copper, etc.  Unless companies can earn a profit, it’s all a big waste of time and money.  Who needs that?  No one reading these articles!

Start With Simple Questions

Start with the fundamentals:  What exactly is this company trying to find or produce—and why do I want exposure to it?

Gold, silver and copper all come out of mines. But are they identical commodities?  No way! Gold is simultaneously a commodity, monetary asset, investment vehicle and store of value.  Yes, all of those.  Copper, aka Doctor Copper, is fundamentally an industrial metal whose demand is closely connected to construction, manufacturing, electrical infrastructure and economic activity.  What about silver?  Silver lives somewhere in between, combining monetary and investment characteristics with substantial industrial demand. Ultimate combo!

That means investing in a junior gold company is not necessarily the same investment thesis as investing in a junior copper company or silver company.  Before evaluating the company, understand the commodity.

A Great Deposit at the Wrong Price

Prices matter enormously because mining companies do not control commodities prices.  They are subservient to the market–supply and demand. 

Consider.  Apple can raise iPhone prices (and they always do). A restaurant can increase the price of dinner.  Can a gold miner simply announce that it will sell gold at another $500?  Nope! Gold prices are set at the world level not at the gold mine.  That creates an interesting investment problem.

Suppose a junior mining company publishes an economic study showing an attractive project at $3,000 gold. What happens if gold falls to $2,300?  Or suppose a copper project looks marginal at $4.00 copper but extraordinarily profitable at $5.50.  What to do? 

The answer depends partly on the commodity-price assumptions underlying the analysis. This is why I don’t evaluate a mining project only at today’s spot price. Mines can take years—or decades—to discover, permit, finance, construct and operate. Today’s commodity price is important. Tomorrow’s may matter more.

Supply and Demand Still Matter

Commodity markets are often shrouded by narratives, not necessarily false ones.  For instance, Copper is essential for electrification. Silver benefits from solar demand. Gold protects against monetary instability. All narratives may contain considerable truth. But a good story is not enough. I want to understand what could change or reinforce the story.

On the supply side: Where does new production come from? How long does it take to develop new mines? Are ore grades declining? Are major producing jurisdictions becoming politically difficult? Is the industry investing enough capital to replace depleted reserves?

Let’s turn to demand. What industries consume the commodity? How sensitive is that demand to economic growth? Can manufacturers substitute another material? How much demand depends on government policy or subsidies? How important is investment demand?

The purpose isn’t to predict commodity prices perfectly.  I can’t. Who can?  No one. The objective is to understand the forces that could move the commodity market—and therefore the value of the company I am considering.

Don’t Confuse a Commodity Thesis with a Company Thesis

This distinction is particularly important.  I can be extremely bullish on copper and still reject a copper company.  Converserly, can I be neutral on gold and find an unusually attractive gold company?  You bet!

Why?  Simple, a good commodity or strong commodity bull market does not automatically make a good company.

Imagine that I believe copper faces a structural supply deficit over the next decade. Which I do. That’s potentially attractive. But the junior copper company I’m examining has low grades, difficult metallurgy, enormous capital requirements and a project located in a jurisdiction where permitting could take years. My copper thesis may be right while my investment is wrong. The SCOREcard forces me to separate those questions.

Quality Matters Within the Commodity

News flash: two gold deposits containing the same number of ounces can have dramatically different economic value. Grade matters. Metallurgy matters. Recovery matters. Strip ratio matters. Infrastructure matters. Depth matters. Energy costs matter.  What’s more, the relevant variables change depending upon the commodity and deposit type.

A copper porphyry containing billions of tones of relatively low-grade material may potentially support an enormous mine. A narrow-vein underground gold deposit presents a completely different engineering and economic problem. This is why commodity analysis cannot simply be:

Gold? Check.

Copper? Check.

Silver? Check.

The commodity must be examined in the context of how that particular deposit can potentially become an economic mine.

Beware of the Commodity Fashion Show

Mining comes into and out of vogue.  When commodity prices rise, investor enthusiasm tends to follow. Suddenly everybody has the commodity the market wants. Currently, rare earths are the rage. 

A company that was focused on gold yesterday may discover that it has a lithium opportunity today. Tomorrow perhaps uranium becomes fashionable. Next year maybe copper That doesn’t automatically mean something improper is happening. Markets change, and good management should recognize opportunities.

But my antenna goes up. Does management genuinely possess expertise in the commodity? Is the geological opportunity legitimate? Does the company have a coherent strategy? Or has management simply discovered which commodity currently attracts financing? The distinction matters. A commodity bull market can finance a good strategy. It shouldn’t substitute for one.

Price Assumptions Should Survive Bad Weather

If nothing else the Mining SCOREcard™  should encourage skepticism toward economic models that only work when everything goes right.  When does everything go right? 

If a project requires historically exceptional commodity prices to generate acceptable returns, red alert.  I prefer: a project that remains economically interesting under conservative assumptions and becomes spectacular under favorable conditions.  Hope is not a strategy. Commodity markets are volatile. Mining investors should expect  and be violent market turbulence–category 4 and 5 hurricane storms!

Commodity Is About Context

The Commodity pillar therefore asks something much deeper (pun intended!) than: What metal is in the ground, it asks:

What drives demand for that commodity? Where does supply come from? How cyclical is the market? What could substitute for it? What commodity price does the project require? How sensitive are project economics to changes in that price? Does this particular deposit possess characteristics that could allow it to compete through different commodity cycles? Those questions help me distinguish between owning a good geological story and owning an economically resilient mineral asset.

The Second Letter in SCOREcard–“C”

The Mining SCOREcard™ begins with people because people allocate capital and make decisions. Then comes the commodity because even excellent management operates within markets it cannot control.

S — Strategy & Stewardship asks whether I trust the people.

C — Commodity asks whether I understand the market in which those people must compete.

Neither question guarantees investment success. Nothing does.  Asking both may avoid a surprisingly common mistake: falling in love with a mineral deposit without asking whether the world will ultimately pay enough for what comes out of it.

Next, I’ll move to the third pillar of the Mining SCOREcard™:  O — Opportunity.  Because once I understand the people and the commodity, I want to know something else:  How much value could actually be sitting there waiting to be created?

Sincerely,

Yogi Nelson

Austrian economics, Banking, Blockchains, Decentralized, finance, International Finance, Mining, platinum, precious-metals, tokenization, Uncategorized

Tokenized Platinum: Built for the Real Economy

by Yogi Nelson


What Makes Platinum Different

  • Extreme scarcity: annual global platinum production averages under 200 metric tons. Annual production of gold is 3,000 metric tons, while silver is approximately 26,000 metric tons.
  • Geographic concentration: roughly three-quarters of supply comes from South Africa, with most of the remainder from Russia. Two nations rather than the 194 worldwide!
  • High production costs: platinum is difficult and expensive to extract and refine
  • Limited substitution: in many applications, platinum has no perfect replacement

Monetary Metal or Industrial Metal? (The Platinum Distinction)

  • Catalytic converters for emissions control
  • Chemical and petroleum refining
  • Medical devices and pharmaceuticals
  • Electronics and data storage
  • Hydrogen fuel cells and clean-energy systems

Why Platinum Is a Natural Fit for Tokenization


Tokenized Platinum vs. Traditional Platinum Products

  • Direct ownership rather than synthetic exposure
  • On-chain transparency of reserves and transfers
  • Programmable compliance and auditability
  • Global reach independent of local financial infrastructure

Real-World Use Cases Beyond Investment


Risks, Constraints, and Realism

  • The market is smaller, increasing volatility
  • Custody standards must remain rigorous
  • Regulatory frameworks vary by jurisdiction
  • Adoption will be gradual rather than explosive

Long-Term Outlook: Platinum’s Quiet Permanence


Sources

World Platinum Investment Council (WPIC) – Platinum Quarterly Market Review
U.S. Geological Survey (USGS) – Mineral Commodity Summaries: Platinum Group Metals
Johnson Matthey – Platinum Group Metals Market Report
International Energy Agency (IEA) – Critical Minerals and Clean Energy Transitions
World Bank – Minerals for Climate Action