Uncategorized

Environment, Social and Governance (ESG): Substance Over Narrative

by Yogi Nelson

ESG in Junior Mining: From Peripheral Topic to Core Risk

Investors in junior mining demand to know how companies plan to address ESG (environment, social, and governance) issues before writing any checks. Essentially, investors, regulators, communities, and strategic partners expect companies to demonstrate awareness of and solutions to environmental and social risks. Paradoxically, the growing prominence of ESG has introduced a new challenge: the risk that ESG becomes a narrative rather than a discipline–and that’s the worse possible outcome.

For junior mining companies, this risk is particularly acute. Limited resources, early-stage projects, and evolving operational systems can create a gap between what a company aspires to be and what it can currently demonstrate. Expectations versus reality. When that gap is filled with overly confident messaging, ESG shifts from an asset to a liability. Boards must therefore approach ESG not as a communications theme, but as a governance responsibility tied directly to risk, credibility, and project viability.
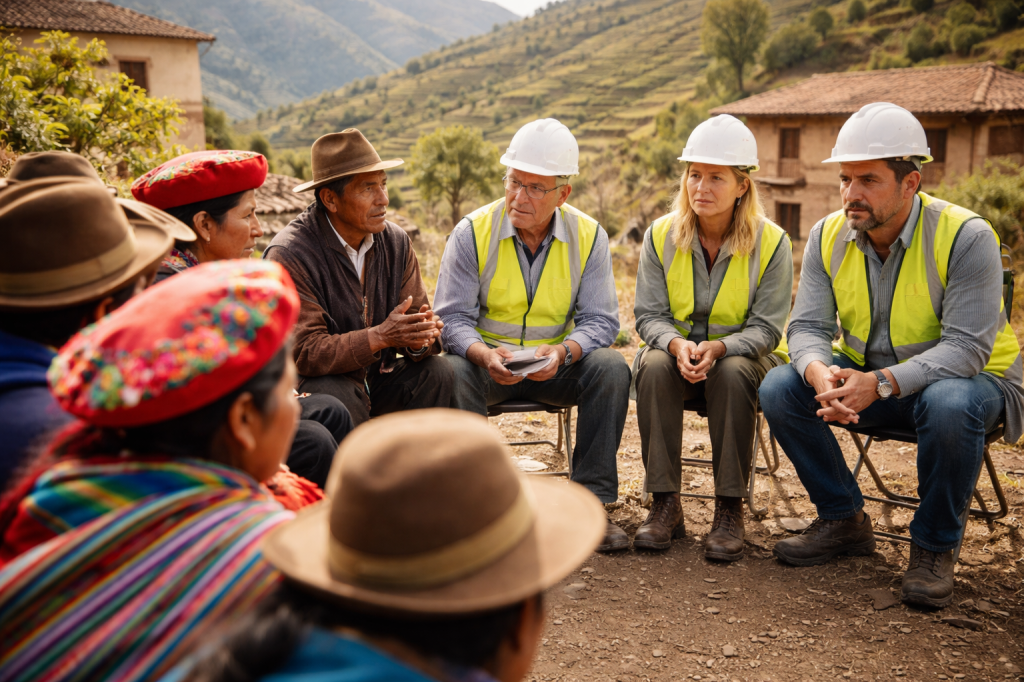
Credible ESG starts with listening—before claims are made, before decisions are taken.

ESG as a Driver of Capital Access

In today’s market, ESG is increasingly linked to access to capital. Institutional investors, strategic partners, and even certain retail investors place greater emphasis on how companies manage environmental and social risks. That is a fact. For junior miners, this has practical implications:

  • Financing discussions will include ESG-related questions
  • Strategic partners will evaluate community relationships before committing capital
  • Analysts will discount companies perceived to carry elevated ESG risk

A weak or unsubstantiated ESG profile can therefore affect valuation, financing terms, and investor confidence. The bottom line shrinks.

Fortunately, markets are more discerning when compared to yesterday. Investors are increasingly able to distinguish between substantiated ESG practices and promotional language. Companies that rely heavily on narrative without supporting evidence may initially attract attention, but over time they risk losing credibility. Smart boards under credibility is expensive–they don’t sell it cheap.

Boards should recognize that ESG is not simply about signaling alignment with investor expectations. It is about demonstrating operational discipline that supports long-term capital formation.

Authentic ESG Reporting

Credibility begins with alignment between disclosure and reality. Authentic ESG reporting does not require a company to present itself as fully developed or without challenges. To the contrary. Overly polished disclosures often raise concern among experienced investors. Astute investors don”t believe hype. What they look for is whether the company’s statements are:

  • Accurate
  • Balanced
  • Supported by observable practices

Boards should encourage management to clearly distinguish between:

  • Current capabilities and future objectives
  • Established practices and initiatives in development

A company that acknowledges where it is in its ESG journey is often more credible than one that suggests it has already achieved a fully mature profile. Measured disclosure builds trust. Overstatement erodes it.

Governance Oversight of Sustainability Claims

ESG claims must be subjected to rigorous governance. The Board must not adopt two standards: one for ESG and one for all other issues. Consider the following: while some community organizations may not have the expertise to understand geology, drill results, etc., all of them are capable of sniffing out public relations puff pieces. Smart boards do not attempt to mislead investors nor the local community.

Boards do not need to approve every communication, but they must ensure that material ESG statements are grounded in evidence. This requires a disciplined approach to reviewing how ESG is presented in:

  • Investor materials
  • Public filings
  • Corporate presentations
  • Website content

If management asserts that the company has strong community engagement, the board should seek specifics. How frequently does engagement occur? Who participates? What issues have been raised? What actions have been taken? Good governance requires moving from general narrative to verifiable detail. Directors should ask:

  • What supports this claim?
  • Is this statement descriptive or aspirational?
  • Has it been verified internally or externally?
  • Is there documentation behind it?

Permitting, Social License, and Project Viability

In junior mining, ESG is not an abstract concept—it directly affects whether a project can advance. Permitting processes are often influenced by:

  • Environmental considerations
  • Community relationships
  • Local and regional political dynamics

A company that underestimates these factors may face delays, increased costs, or even an inability to proceed. The concept of a “social license to operate” is sometimes discussed loosely, but its practical meaning is clear. Projects that lack community support or encounter persistent opposition can become significantly impaired, regardless of their geological quality.

Boards should therefore view ESG not as a reputational issue, but as a determinant of project feasibility.

The Gap Between Narrative and Field Reality

One of the most common governance risks in ESG arises from a disconnect between head office messaging and field-level reality. What I call, “lost in translation” phenomenon. Here is what often happens.

Management teams may present ESG narratives based on intentions, policies, or limited interactions, while conditions on the ground are more complex. Often far more complex that can be described in a power point slide deck. Community concerns may be evolving, relationships may be uneven, and engagement may be less structured than described. Boards should be attentive to this potential gap by asking probing questions. For instance and actions steps:

  • Direct reporting from operational teams
  • Evidence of consistent engagement practices
  • Confirmation that field realities are accurately reflected in disclosures
  • Site visits

Without this alignment, the company risks presenting a version of itself that cannot be sustained under scrutiny.

The Importance of Community Engagement Documentation

Documentation is what transforms ESG from a concept into a governance practice. Management must document their positive and negative community relations interactions. Boards should ensure the company maintains structured records of:

  • Community meetings and participation (also who didn’t attend who should have because their absence might be equally important)
  • Issues and concerns raised by stakeholders
  • Commitments made by the company
  • Follow-up actions and outcomes

This documentation serves several critical functions:

  • It provides evidence supporting ESG disclosures
  • It creates accountability within management
  • It allows the board to monitor patterns and emerging risks
  • It protects the company in the event of disputes or challenges

Without documentation, ESG claims remain difficult to substantiate.

Avoiding Reputational and Governance Exposure

Reputational exposure often begins with overstatement. Don’t over promise and under deliver. Do the oppose. A company may believe it is strengthening its profile by emphasizing ESG in communications. However, once expectations are established, they can be tested by:

  • Investors
  • Regulators
  • Communities
  • External observers

If claims are found to be exaggerated or unsupported, the consequences can extend beyond ESG:

  • Management credibility may be questioned
  • Board oversight may come under scrutiny
  • Other disclosures may be viewed with skepticism

In extreme cases, misleading ESG statements could contribute to legal or regulatory exposure, particularly if they influence investment decisions. Boards should therefore approach ESG disclosures with the same discipline applied to financial reporting.

Substance Over Narrative in Practice

ESG becomes meaningful when it is integrated into everyday operations and becomes part of the organization’s culture. Boards must look for evidence that sustainability considerations are reflected in:

  • Operational procedures
  • Internal reporting systems
  • Risk management frameworks
  • Incentive structures

Communities and stakeholders evaluate companies based on conduct, not language. They observe whether the company listens, responds, and follows through. Similarly, investors increasingly reward companies that demonstrate consistency and discipline rather than those that rely on broad narratives.

A company that communicates carefully, documents thoroughly, and acts consistently will be viewed as more credible than one that presents an expansive but unsupported ESG profile.

Final Thoughts

For directors of successful junior mining companies, ESG is not a peripheral issue. It is a governance subject that directly affects credibility, capital access, and project viability. The board’s responsibility is to ensure alignment between disclosure and reality, to require evidence behind material claims, and to encourage disciplined, measured communication. In doing so, the board protects both the company’s reputation and its strategic position.

In an environment where markets increasingly distinguish between commitment and marketing, the most effective ESG approach is not the most elaborate. It is the most credible.

Substance over narrative is not simply a communication preference. It is a governance necessity.

Until next time,

Yogi Nelson
Blockchains, Copper, Gold, Mining, Tether, tokenization, Yogi Nelson

One Token, Many Metals: The Promise—and Limits—of Digital Metal Baskets

by Yogi Nelson (Nelson Hernandez)

From Single Metals to Structured Exposure

The first wave of tokenized metals has focused on individual assets—gold, silver, and to a lesser extent, platinum and palladium. These instruments mirror traditional bullion ownership, simply wrapped in a digital format. Do investors think in single assets? Rarely. Instead, they think in portfolios. If that’s true, the next natural question is:

What if tokenized metals could be combined into a single, structured instrument—much like an ETF—offering diversified exposure across multiple metals? In other words, a multi-metal token basket, e.g. a digital equivalent of a metals ETF. Let’s explore that concept next.


What Is a Multi-Metal Token Basket?

At its core, a multi-metal token basket is a single digital token representing proportional ownership in multiple underlying metals. A combo token. For example, a token could represent:

  • 50% gold
  • 25% silver
  • 15% copper
  • 10% platinum

Each component would be backed by physical metal held in custody, with allocations transparently tracked on a blockchain. Rather than holding multiple tokens—or managing separate exposures—investors would hold one instrument with built-in diversification. In effect, it simplifies access while preserving the underlying asset integrity.


What Is a “Digital Metals ETF”?

The term “ETF” is familiar for a reason. Traditional metals ETFs—such as those holding gold or silver—provide investors with exposure without requiring physical custody. They trade on regulated exchanges and offer liquidity, pricing transparency, and ease of access. A digital metals ETF would aim to replicate these benefits—but through tokenization. Same idea; new and better technology.

Instead of shares traded on an exchange like the New York Stock Exchange or NASDAQ, ownership would be represented by blockchain-based tokens. That means settlement could be:

  • Near-instant
  • Cross-border
  • Potentially 24/7

The result is a hybrid ETF with built in diversification of an ETF, that features the flexibility of digital assets.


Why Investors May Find It Attractive

The appeal of a multi-metal token basket is straightforward—but powerful. Consider these five attractions below:

Diversification in a Single Instrument
Instead of allocating separately to gold, silver, and industrial metals, investors gain exposure across the spectrum in one position.

Simplicity
Portfolio construction becomes easier. One token replaces multiple holdings. One instrument replaces multiple transactions.

Accessibility
Tokenized instruments can lower barriers to entry, allowing fractional ownership and global participation. If widely adopted, this would mean more liquidity and more efficient price discovery. Moreover, tokenized assets can be accessed across borders without traditional brokerage constraints.

Transparency
Blockchain-based tracking could provide greater visibility into:

  • Metal reserves
  • Allocation ratios
  • Custody arrangements

Portfolio Flexibility
Depending on structure, baskets could be:

  • Static (fixed allocation)
  • Dynamic (adjusted periodically based on market conditions)

Innovation
Programmability opens the door to:

  • Rebalancing mechanisms
  • Yield overlays
  • Integrated collateralization

In short, it brings institutional-style portfolio construction into a more flexible, digital format.


Where Would It Trade?

This is where things become more complex. A traditional ETF is listed on regulated exchanges such as the New York Stock Exchange or NASDAQ. Is it possible to create a multi-asset ETF of tokenized metals? Yes. Would it be easy; probably not. If the NYSE is not viable, a digital metals ETF could follow one of several paths:

Crypto Exchanges
Platforms such as Coinbase or Kraken could list tokenized baskets.

  • Pros: global access, liquidity, 24/7 trading
  • Cons: regulatory uncertainty, investor protections

Hybrid Platforms
Emerging regulated digital asset exchanges could bridge traditional finance and blockchain.

Tokenized Securities Platforms
Some jurisdictions may allow tokenized ETFs to trade as regulated securities.

The likely outcome is a fragmented landscape initially, with convergence over time.


Limitations

Are there real challenge? Yes—and they should not be overlooked.

Complexity Beneath Simplicity
While the front-end appears simple, the back-end becomes more complex:

  • Multiple metals
  • Multiple custodians
  • Multiple jurisdictions

Custody and Verification
Each component must be:

  • Verified
  • Audited
  • Securely stored

The more assets in the basket, the greater the operational burden.

Regulatory Uncertainty or What is it?

  • A commodity?
  • A security?
  • A hybrid instrument?

Different jurisdictions may answer differently.

Redemption Challenges
Redeeming physical metal from a basket could be:

  • Complicated
  • Costly
  • Limited by thresholds

Correlation Risk
Not all metals behave the same way:

  • Gold may rise during instability
  • Industrial metals may fall

A fixed basket may dilute performance in certain conditions.


When Might This Happen?

The idea is not far-fetched—but timing matters. We are already seeing:

  • Tokenized gold and silver gaining traction
  • Increased institutional interest in real-world assets (RWAs)
  • Regulatory frameworks beginning to evolve

A multi-metal token basket could emerge in stages:

Phase 1: Experimental Products
Niche offerings on crypto platforms

Phase 2: Structured Products
More refined baskets with clearer custody and audit frameworks

Phase 3: Institutional Adoption
Integration into regulated markets and broader portfolios

A realistic timeline:

Early versions within 1–3 years
More mature, widely accepted structures within 5–10 years


Which Blockchain Is Best Suited?

This is not a trivial question. The underlying blockchain must support:

  • Security
  • Transparency
  • Scalability
  • Regulatory compliance

Several candidates stand out:

Ethereum

  • Strong ecosystem
  • Widely adopted
  • High security
  • Potentially higher transaction costs

Polygon

  • Lower costs
  • Faster transactions
  • Built on Ethereum infrastructure

Cardano

  • High speed
  • Low cost
  • Secure
  • Privacy layers

Permissioned Blockchains
Private or consortium chains may appeal to:

  • Institutional investors
  • Regulators
  • Custodians

The likely outcome is a mix of public and permissioned systems, depending on use case.


The Bigger Question: Is This Needed?

Do investors actually need a digital metals ETF? Or is this simply innovation for its own sake—a repackaging of existing structures? The answer likely lies in execution.

If tokenized baskets:

  • Improve transparency
  • Reduce friction
  • Enhance access

Then they add value. If they simply replicate ETFs with added complexity, their adoption may be limited.


Final Thoughts

The evolution from single-metal tokens to multi-metal baskets is logical. It mirrors the broader progression of financial markets:

  • From individual assets
  • To structured products
  • To diversified portfolios

Multi-metal token baskets represent the next step in that journey. They offer:

  • Simplicity at the surface
  • Complexity beneath
  • Opportunity—if executed well

If executed correctly the concept could become a foundational instrument in digital asset markets. On the other hand, get it wrong, and they risk becoming another layer of structure—without meaningful improvement.

The idea is compelling. The execution will determine everything.


Until next time,


Yogi Nelson (Nelson Hernandez)

Blockchains, finance, Mining, Nickel, tokenization, Yogi Nelson

Tokenized Nickel: A Critical Metal for the Clean Energy Transition

by Yogi Nelson (Nelson Hernandez)

Nickel rarely gets the attention it deserves. It does not carry the mystique of gold or the narrative momentum of lithium. Yet quietly, nickel is becoming one of the most important metals in the global economy.

Why? Because it sits at the intersection of two powerful forces:

  • Industrial production (stainless steel)
  • The clean energy transition (EV batteries)

👉 Roughly 65–70% of nickel goes into stainless steel
👉 But the fastest growth is coming from electric vehicles and energy storage

So the question becomes:

Can nickel be tokenized?

In theory—yes.

Nickel benefits from:

  • Global liquidity (LME markets)
  • Established warehouse systems
  • Broad industrial demand

But in practice, it is more complicated.

Nickel exists in multiple grades and forms, each with different uses and values.
It moves through complex global supply chains.

👉 That makes tokenization less about retail investing…
…and more about industrial efficiency, tracking, and coordination.

If tokenized nickel works, it won’t be because investors demand it.

It will be because the system requires it.

And as always:

Structure—not story—will determine what works.

Yogi Nelson (Nelson Hernandez)

Board of Directors, Environment, Governance, Mining, Risk Management, Yogi Nelson

Governance Before Revenue: Jurisdictional and Cross-Border Risk Oversight

by Yogi Nelson

Why Geography Requires Governance Discipline

Mining spans the globe. Mineral deposits do not appear conveniently inside “stable” jurisdictions with predictable legal systems and transparent regulatory frameworks. Even the so-called “stable” jurisdictions can be unpredictable occasionally. Unfortunately, some of the world’s most promising geological opportunities are located in regions where political systems are evolving, regulatory regimes are complex, and governance expectations vary widely.

Regardless of preference, miners must go where the earth has placed deposits. That is why junior—and major—mining companies must pursue opportunities in emerging markets. Geological potential can be extraordinary. However, the opportunity comes with an additional layer of risk: jurisdictional exposure.

For boards of directors, this reality introduces an important governance responsibility. Geological potential alone cannot guide investment decisions. Boards must ensure that jurisdictional risk receives the same disciplined oversight as exploration strategy, capital allocation, and financial reporting. In other words, geology may attract investors—but governance keeps them invested.

Smart boards evaluate geology and jurisdiction with equal discipline.


The Nature of Jurisdictional Risk

Jurisdictional risk refers to the political, legal, regulatory, and social uncertainties associated with operating in a particular country or region. These risks include, but are not limited to, the following:

  • Political instability
  • Regulatory unpredictability
  • Corruption
  • Weak rule of law
  • Changing tax or royalty regimes
  • Community conflict
  • Criminal gangs
  • Wars

Large multinational mining companies have the resources to support dedicated risk teams—either internally or via outside consultancy—to monitor these factors. Junior mining companies rarely have that luxury. Why? Management teams are smaller and their administrative infrastructure leaner.

That reality places a greater responsibility on the board of directors to ensure that jurisdictional exposure is carefully evaluated and monitored. After all, the greatest geological discovery in the world cannot create shareholder value if the operating environment becomes unstable or hostile.


Anti-Corruption Frameworks

One of the most important governance considerations when operating across borders is corruption risk. Actually, based on my 30+ years working in government in the USA, corruption considerations apply to the USA as well. In this article, however, the focus will be outside the United States. Many jurisdictions where mining occurs have different norms regarding government interaction, permitting processes, and local business practices.

Public companies listed in North America or Europe, however, remain subject to strict anti-corruption laws such as the Foreign Corrupt Practices Act (FCPA) in the United States and the UK Bribery Act. These regulations apply regardless of where the mining activity occurs. Boards must therefore ensure that management implements appropriate compliance structures, including:

Clear anti-corruption policies

Employee training regarding prohibited practices

Documentation of interactions with government officials

Internal reporting procedures for potential violations

These safeguards are not bureaucratic formalities. Violations of anti-corruption laws can result in severe financial penalties, reputational damage, and loss of investor confidence. Governance discipline begins with prevention, not remedy.


Local Partner Due Diligence

Out of necessity and common sense, junior mining companies often work with local partners when entering new jurisdictions. Quality local partners have the expertise to effectively manage permitting processes, land access, community relations, or logistical support that are specific to the task at hand. Such partnerships can be valuable—sometimes essential. Do they come with risk? Yes.

Boards must ensure that management conducts thorough due diligence before entering into agreements with local partners—actually with all partners regardless of jurisdiction. This process typically includes, at a minimum, reviewing:

  • Ownership structures
  • Political connections
  • Business reputation
  • Financial stability
  • Past legal and regulatory issues

Failure to perform adequate due diligence can expose the company to significant legal and reputational risk. In many cases, governance failures in emerging markets do not originate from the mining company itself. But that does not make any material difference. The problem exists. The issue may originate from poorly vetted local intermediaries. Right or wrong, these local intermediaries reflect on the mining company.

In other words, you pick them, you are stuck with them.

A disciplined board ensures that partnerships strengthen operations rather than create vulnerabilities.


Monitoring Geopolitical Exposure

Political environments can change quickly. Elections shift policy priorities. Governments revise mining codes based on election results—or the threat of an election result. National resource strategies evolve. Boards must therefore monitor geopolitical developments continuously rather than assuming that current conditions will remain stable.

Is it wise to contract with politically connected persons? Some might say yes. Prudence says beware. Those on the inside today might be on the outside tomorrow. With that as a note of caution, best practices in oversight often include reviewing:

  • Changes in mining legislation
  • Tax and royalty adjustments
  • Resource nationalism trends
  • Local election outcomes
  • Regional security conditions

While none of these developments are within the control of a mining company, that does not mean they can be ignored. To the contrary, they must be understood. Boards that monitor geopolitical developments proactively are better prepared to adapt when conditions change. Those that ignore these signals often discover the risks only after they materialize.


Community and Social License Considerations

Jurisdictional risk is not limited to government policy. Community relationships play an equally important role in determining whether a mining project can advance successfully. A strong argument can be made that government policy is often the sum of community relations. Establish and maintain healthy community relations and government policy will likely break in favor of the mining company.

Exploration and development activities often occur near local communities that rely on land, water, and environmental stability for their livelihoods. If community concerns are not addressed early, projects can encounter delays, protests, or legal challenges. Once an opposition narrative takes root, weeding it out may be impossible.

Therefore boards should encourage management to maintain transparent and respectful engagement with local communities. Below are a few best practices:

  • Community consultation practices
  • Environmental impact mitigation strategies
  • Local employment and training commitments
  • Community investment initiatives

Responsible engagement strengthens a company’s social license to operate. And social license, while difficult to measure on a balance sheet, can determine whether a project ultimately moves forward. The bottom line is this: establish and maintain healthy community relations and government policy will likely break in favor of the mining company.


Board-Level Oversight of Jurisdictional Exposure

Jurisdictional risk oversight should not be treated as an occasional discussion item. It should be integrated into regular board deliberations. A standing agenda item. The agenda item should consider:

  • Updated country risk assessments
  • Political developments affecting operations
  • Regulatory changes
  • Compliance and anti-corruption reports
  • Community relations updates

These discussions allow the board to understand how external factors may influence the company’s strategic decisions. Importantly, oversight does not mean avoiding emerging markets entirely.

In some cases, for example silver mining, Mexico and Peru cannot be avoided. Many successful mining companies operate in Mexico and Peru. Yes, those jurisdictions may appear complex or uncertain, but with proper board governance smart decisions are possible.

In other words, the objective is not avoidance—it is preparedness.


Governance as Risk Discipline

Mining companies cannot control where mineral deposits occur. What can they control? How responsibly they operate after deciding to enter a jurisdiction.

Strong governance structures provide the discipline necessary to manage complex environments. Boards that take jurisdictional risk seriously encourage management to adopt professional compliance practices, maintain transparent relationships with regulators and communities, and anticipate geopolitical developments.

Companies that ignore these governance responsibilities often encounter difficulties later.

Remember this—markets have long memories when governance failures occur.


Final Thoughts

Many of the world’s most attractive mineral opportunities exist in jurisdictions where political, regulatory, and social dynamics require careful navigation. This may be a considerable understatement. Junior mining companies pursuing these opportunities must therefore match geological ambition with governance discipline. Boards that oversee jurisdictional exposure thoughtfully protect not only the company’s operations but also its credibility in capital markets.

Get the geology right and the project may succeed. Get the governance right and investors stay with you long enough to see it through. In the global mining industry, both are essential.


Until next time,


Yogi Nelson

Blockchains, Environment, finance, Governance, Mining, Nickel, tokenization, Uncategorized, Yogi Nelson

Tokenized Nickel: A Critical Metal for the Clean Energy Transition

by Yogi Nelson (Nelson Hernandez)

Nickel seldom demands the spotlight. It infrequently carries the mystique of gold, the dual identity of silver, or even the growing narrative momentum of copper and lithium. Yet beneath that relative obscurity lies a reality that is becoming increasingly difficult to ignore: nickel is a foundational material in the clean energy transition.

It plays a central role in battery chemistry, industrial production, and the infrastructure of a modern, electrified economy. And as demand accelerates, so too does the complexity of its supply chain. This raises a familiar—but evolving—question:

Can a metal defined by industrial use, chemical variation, and global fragmentation be effectively tokenized on the blockchain?

Or more precisely: Is nickel another candidate for tokenization—or a reminder that not all critical materials are easily digitized? Those questions and others to be answered below, but first what is nickel?


What Is Nickel?

Nickel is a silvery-white metal known for its strength, corrosion resistance, and high-temperature stability. It has been used for over a century in industrial applications, but its importance has grown significantly in recent decades. What are its properties:

  • Resistance to corrosion and oxidation
  • High melting point
  • Strength and durability
  • Ability to form alloys with other metals

Nickel is rarely used in pure form. Instead, it is typically combined with other metals to enhance performance characteristics.


Where Is Nickel Mined?

Nickel production is geographically concentrated, with a few countries dominating global supply.

Major producers in order of production include:

  • Indonesia — the world’s largest producer, with rapidly expanding output
  • Philippines — significant supplier of laterite nickel ore
  • Russia — major producer, particularly of high-grade nickel
  • Canada — stable and high-quality production
  • Australia — significant reserves and mining operations

Nickel is extracted from two primary types of deposits:

  • Sulfide deposits (higher grade, easier to process)
  • Laterite deposits (more abundant, but more complex and energy-intensive to refine)

This distinction matters because:

  • Not all nickel is equal
  • Processing methods affect cost, quality, and usability

What Is Nickel Used For?

Nickel’s value lies in its versatility. Nickel stands as the fifth most commonly used metal behind: iron, copper, aluminum, and silver.

1. Stainless Steel (Primary Use)

Approximately 65–70% of global nickel demand is tied to stainless steel production. When iron is transformed into steel, nickel joins the production process. Nickel is used to improve corrosion resistance, strengthen toughness, and performance at high and low temperatures. Here is a short list of uses:

  • Used in construction
  • Industrial equipment
  • Consumer goods

This is the traditional foundation of nickel demand.


2. Batteries (Fastest Growing Use)

Nickel is a key component in lithium-ion battery chemistries, particularly:

  • Nickel-Manganese-Cobalt (NMC)
  • Nickel-Cobalt-Aluminum (NCA)

Higher nickel content in batteries results in:

  • Increases energy density
  • Extends vehicle range

This is why nickel is central to electric vehicles. Tesla, BYD, and all EV manufacturers need nickel. No nickel no EVs.


3. Energy and Industrial Applications

Nickel is also used in:

  • Aerospace alloys
  • Turbines and power generation
  • Chemical processing equipment

Nickel is both an industrial and strategic material. Recognizing the importance of nickel, the US government listed nickel as a critical mineral in 2022.


Why Nickel Demand Is Rising

Nickel demand is being pulled in two directions simultaneously:

1. Traditional Industrial Demand

  • Infrastructure development
  • Manufacturing growth
  • Stainless steel consumption

2. Energy Transition Demand

  • Electric vehicles
  • Battery storage systems
  • Renewable energy infrastructure

Nickel demand for batteries alone is expected to grow significantly over the next decade, driven by EV adoption and energy storage needs. This creates a dual-demand structure:

  • Stable base demand
  • Rapidly expanding new demand

Why Nickel Is a Candidate for Tokenization

Nickel presents an interesting—but complex—case for tokenization.

Unlike gold, or even silver to some extent, tokenization is not about preserving value. And as opposed to lithium, nickel is not purely about energy storage. Despite sitting outside of those considerations, there may be reasons for tokenization. Let’s examine those below.


1. Global Liquidity

Nickel is actively traded on major exchanges, including the London Metal Exchange (LME). This provides:

  • Price discovery
  • Market depth
  • Existing financial infrastructure

For tokenization to work effectively liquidity must be present in the market place. The nickel market has liquidity.


2. Industrial Relevance

Nickel is essential across multiple sectors:

  • Construction
  • Manufacturing
  • Energy

This broad utility supports:

  • Consistent demand
  • Ongoing market activity

Liquidity and industrial relevance push the possibility of tokenized nickel toward viability. Let’s go to step three.


3. Warehouse and Inventory Systems

Nickel is already stored in:

  • Exchange-approved warehouses
  • Industrial storage facilities

This creates a potential foundation for:

  • Token-backed inventory models
  • Digitized ownership

Warehouse and inventory systems combined with liquidity and industrial relevance create the environment where tokenization is possible. Yet, there is one more factor–strategic importance. Nickel is valued by major economic and military powers.


4. Strategic Importance

Nickel is a critical mineral, according to the US government, European Union, Canada, Australia, Japan, United Kingdom, India, and China. There may be others, but you get the point. In other words, every major economic power. Russia is missing most likely because they are a major silver producer and therefore are not concerned with securing supply. As a critical mineral that means governments are monitoring supply chains and nations have or will develop supportive policy frameworks.

This increases demand for:

  • Transparency
  • Traceability
  • Verification

How Tokenized Nickel Might Work

Tokenization of nickel would likely follow several possible models.


1. Warehouse-Backed Tokens

  • Each token represents a specific quantity of nickel
  • Stored in verified facilities
  • Audited regularly

Similar to gold—but with more complexity. Sophisticated players only.


2. Supply Chain Tracking

Tokens track nickel through stages:

  • Mining
  • Processing
  • Manufacturing

This could improve:

  • Transparency
  • Efficiency
  • Coordination

3. Contract-Based Tokenization

Tokens tied to:

  • Future production
  • Offtake agreements

This introduces:

  • Financing opportunities
  • Legal complexity

The Case AGAINST Tokenizing Nickel

❌ Variability in Material

Nickel exists in multiple forms and grades:

  • Class 1 nickel (high purity, battery-grade)
  • Class 2 nickel (lower purity, stainless steel use)

This complicates standardization and tokenizations works best under standardized conditions.


❌ Processing Complexity

The value of nickel depends heavily on:

  • Refining method
  • End-use application

Tokens must reflect these differences accurately. The solution might include NFTs.


❌ Supply Chain Fragmentation

Nickel moves through multiple jurisdictions and stages. Tracking this reliably is difficult albeit not impossible.


❌ Limited Retail Investment Appeal

Unlike gold, nickel is not held as an investment asset. Thus, tokenization may be driven more by specialized industry users than investors.


Governance Considerations

As with all tokenized metals, governance is central.

Key issues include:

  • Proof of reserves
  • Audit transparency
  • Legal ownership rights
  • Redemption mechanisms

In nickel, these issues are amplified by:

  • Multiple grades and classifications
  • Complex processing chains
  • Cross-border logistics

Without strong governance, tokenized nickel risks becoming:

  • Technically feasible
  • Practically unreliable

Final Thoughts

Nickel occupies a unique position in the evolving tokenization landscape. Nickel is:

  • Industrial
  • Strategic
  • Increasingly essential

But it is also:

  • Variable
  • Complex
  • Difficult to standardize

Tokenizing nickel is not about creating a new digital asset for investors. It is about improving how a critical material moves through the global economy. If tokenization succeeds it won’t be due to retail market enthusiasm. Nope. It will be because the industrial system demands:

  • Greater efficiency
  • Better transparency
  • Stronger coordination

And as always:

Structure—not story—will determine whether tokenized nickel becomes a meaningful innovation—or simply another digital experiment.


Until next time,


Yogi Nelson (Nelson Hernandez)